Home
← Buying with Raleigh Realty

First-time homebuyers · Raleigh & the Triangle

Your first home.
Start with
clear answers.

What can you comfortably spend? What happens after an offer? And what does “due diligence” mean for your money? Let’s work through it.

HomesRaleigh is Raleigh Realty’s sister site. Your real estate team is Raleigh Realty.

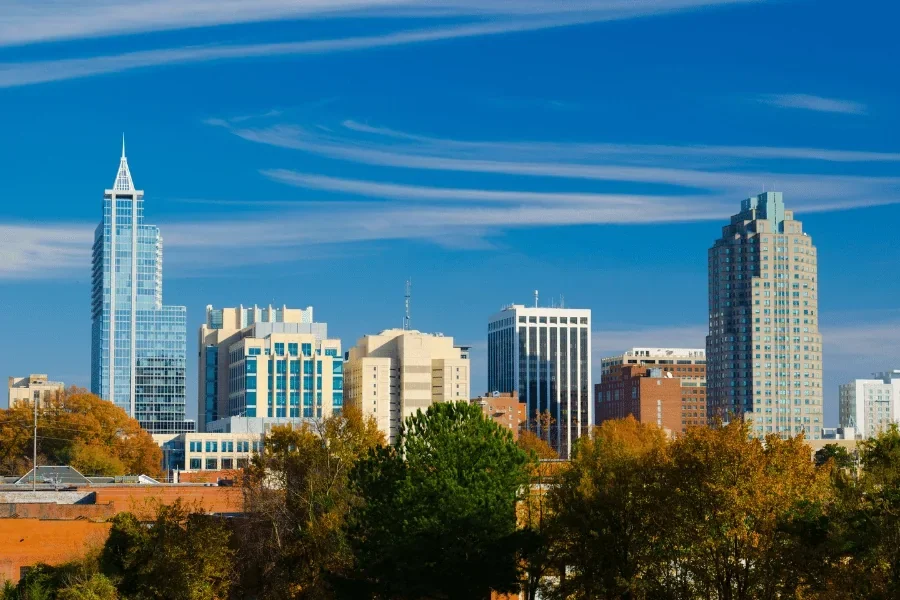
Downtown Raleigh’s skyline above the trees
Raleigh, North CarolinaFrom first questions
to your first home.
Raleigh Realty · Raleigh & the Triangle

Before the first tour

Start with
three numbers.

A lender can discuss what you qualify to borrow. You decide what leaves room for the rest of your life.

01 / Each month

Your comfortable payment

Include principal and interest, property taxes, insurance and any mortgage insurance or association dues. Ask which costs are included in the lender’s estimate and which you pay separately.

Ask: “What would my total monthly housing cost be for this address?”

02 / What to set aside

Your cash before
and at closing

Plan for the down payment, closing costs, inspections and contract deposits. Ask your lender and agent when each payment is due and which amounts are credited at closing, so you don’t count them twice.

Ask: “How much do I need, and when do I need it?”

03 / After the move

Your money left over

Decide what to keep available for moving, repairs and other unexpected expenses. A purchase price can fit the loan and still feel uncomfortable once you move in.

Ask: “What will I have left after closing?”

Use the CFPB’s Loan Estimate explainer
Preapproval, in plain language

A preapproval is a lender’s tentative offer to lend, based on information reviewed so far. It is not a guaranteed loan. Ask about conditions, the expiration date and what still needs approval.

Read the CFPB’s preapproval guide ↗

Before you tour

Know who’s
working for you.

Before arranging tours, talk through your written buyer agreement. NAR’s policy requires MLS participants working with a buyer to have one before touring a home together.

Visiting an open house on your own or asking an agent about their services doesn’t require that agreement under NAR’s guidance.

Read NAR’s buyer-agreement guide ↗
  1. 01 / Services

    What will my agent do?

    Discuss the services included, when representation begins and whether the agreement limits working with other agents.

  2. 02 / Compensation

    What could I owe?

    Fees are negotiable. Review the amount, who may pay and your responsibility if a seller contribution doesn’t cover it. Seller payment is not automatic.

  3. 03 / Duration

    How long am I committing?

    Read the start and end dates and the conditions for changing or ending the agreement before signing.

Before you make an offer

Price is only
part of the offer.

Discuss the price alongside financing, any requested seller-paid costs, the due diligence fee, earnest money, the investigation period and closing date. Consider the home, your finances and what is known about other offers.

Ask your agent: “Which terms fit this home—and what could put my money at risk?”

Ready to discuss an offer? Explore the offer guide

North Carolina · Before you sign

Two payments.
Different rules.

Under North Carolina’s commonly used Offer to Purchase and Contract, the due diligence fee and earnest money have different jobs. Review your actual contract with your agent and closing attorney.

Paid to the seller

Due diligence fee

A negotiated fee for the opportunity to investigate the home and transaction. If you terminate during due diligence, it is generally not refunded, subject to the contract’s exceptions. It is credited toward the purchase price if you close.

Held as a deposit

Earnest money

A separate deposit. A timely written termination during the due diligence period generally allows its return. After that deadline, it may be at risk. The contract controls the conditions for its release.

Put the deadline on your calendar.

Plan time for inspections, financing, appraisal, document review and any repair discussions. Don’t assume a loan problem or an inspection finding automatically cancels the contract or returns your money.

NC Real Estate Commission: due diligence explained ↗

The home and the day-to-day

Check the address.
Not just the photos.

Bring the same questions to a Raleigh condo, a Cary townhome or a house farther out in Wake County. The answers belong to the specific property.

What will this home cost to own?

Check the property’s taxes, insurance, utilities and maintenance needs. For a condo or HOA property, review current dues, what they cover, your responsibilities, restrictions and planned assessments. The monthly dues alone don’t tell the whole story.

Bring the documents to your agent, attorney and insurance provider.

Does this location work for my routine?

If you’ll travel from Buffaloe Road to downtown Raleigh, test that trip. If your destination is Research Triangle Park, test that route instead. Visit at the times you expect to travel and check the errands you make regularly.

A city name or “near RTP” label is only a starting point.

What needs a closer inspection?

Ask a licensed inspector about the home’s condition and any specialist evaluations. For a property with a well or septic system, discuss those inspections too. A new or renovated home still deserves an inspection.

NCREC’s buyer investigation guide (PDF) ↗

Your first-home checklist

A few answers.
A stronger start.

Check what you’ve worked through. Leave the rest as questions to bring to your lender or agent.

0 of 6 reviewedPreparation, at your pace.

Checks stay in this browser tab. They don’t assess loan eligibility or send an inquiry.

Topics I have worked through

Financing questions

Could assistance
be part of your plan?

Ask a participating lender about current eligibility, available funds, repayment rules and the total cost of the loan. Assistance programs have conditions; “first-time buyer” alone doesn’t establish eligibility.

When a home is under contract

Keep the next steps visible.

  1. InvestigateCoordinate inspections, documents, financing, appraisal and any repair discussions before the relevant contract deadlines.
  2. Prepare to closeRespond to lender and attorney requests. Compare your Closing Disclosure with your latest Loan Estimate, including cash to close, and ask about changes.
  3. Walk throughSee the home again before closing. Check its condition and agreed repair items, and confirm possession and key arrangements.
CFPB: what to check in your Closing Disclosure ↗

A real conversation

Your first question
is enough.

Tell the Raleigh Realty team what you’re working through: a starting budget, an area, a home or an unfamiliar contract term.

HomesRaleigh connects you with Raleigh Realty, serving Raleigh and the Triangle.

Meet the team →Read client experiences →Browse homes →

Guide reviewed September 21, 2026. This guide is a starting point; your contract, property and financing require their own review.

← Back to buying with Raleigh Realty

Ask a first-home question

I agree to be contacted by HomesRaleigh via call, email, and text for real estate services. To opt out, you can reply 'stop' at any time or reply 'help' for assistance. You can also click the unsubscribe link in the emails. Message and data rates may apply. Message frequency may vary. For more information, please review our Privacy Policy.
Request a home value review.
Enter your email and choose “Check Now” to open the request form for Raleigh Realty. You’ll add your home address and contact details before submitting.